Call For a Consultation (305) 373-4400
What Is a Credit Bust-Out Scam? How Car Buyers End Up Facing Financial and Criminal Fallout
Executive Summary: Credit bust-out scams involving vehicle financing and car-sharing platforms are increasing nationwide. These schemes typically involve fraudulent loan applications, multiple financed vehicles, and promises of rental income that quickly collapse. Victims often include both individual buyers and dealerships. Because these cases frequently involve bank fraud and wire fraud allegations, they can become serious federal criminal investigations.
Someone approaches you with what sounds like a business opportunity. They tell you they’ve figured out a way to make passive income through car rentals. They explain that platforms like Turo allow private owners to rent out vehicles just like a traditional rental company.
All you have to do is buy the cars in your name. They promise the rental income will cover:
- The car payments
- Insurance
- Tolls
- Parking fees
- And leave you with profit on top of it
For many people, it sounds legitimate. Until the payments stop, the cars disappear, and law enforcement starts asking questions.
This is commonly called a credit bust-out scam, and it is becoming a serious problem across the country.
1. How Does a Credit Bust-Out Scam Work?
The structure is usually similar from case to case.
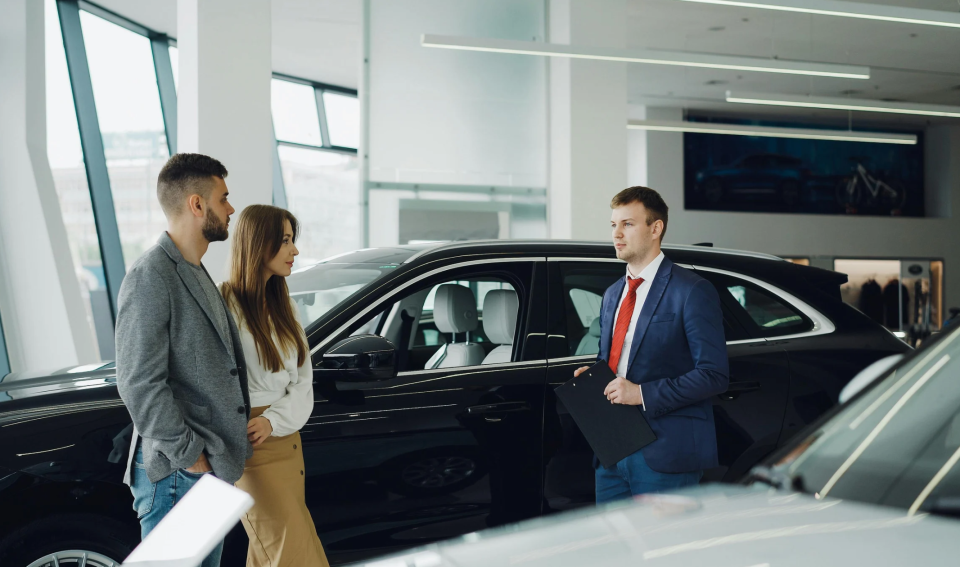
The person running the scheme recruits individuals with decent credit. Those individuals are then taken to dealerships to buy one, two, three, or even four vehicles within a short period of time.
The fraud often begins with the credit applications.
Income is inflated. Job titles are exaggerated. A restaurant employee suddenly becomes “management.” A nurse becomes a “hospital administrator.” The applications make it appear that the buyer earns substantially more money than they actually do.
The vehicles are financed based on false information. Then, before the first loans appear on updated credit reports—which often takes around 30 days—the same person pushes the buyer to finance additional cars.
2. Why Platforms Like Turo Are Being Used
Platforms like Turo are legitimate businesses. They allow private vehicle owners to rent cars directly to consumers. But scammers have realized these platforms create an appearance of legitimacy. Victims are told:
- The cars will generate rental income
- The business model is proven
- Everything will be professionally managed
- They will split profits 50/50
Most of the time, there are no written agreements. No corporate records. No protection for the buyer whose name is actually on the loan. That becomes a major problem later.
3. What Happens After the Cars Are Purchased?
Typically, the organizer makes payments for a short time, sometimes only one or two months. Then they disappear. The buyers suddenly realize:
- The cars are still financed in their names
- The payments are overdue
- The insurance may have lapsed
- The vehicles cannot be located
Some cars are repossessed. Others vanish completely.
Meanwhile, the individuals who signed for the vehicles are left holding the debt. Their credit is destroyed, collection actions begin, and in some cases they become subjects of criminal investigations themselves because false information appeared on financing documents.
4. Why Dealerships Also Become Victims
Many people assume only the individual buyers lose money. That’s not true. Car dealerships often suffer major financial damage too.
Most dealerships have agreements with financing companies requiring them to stand behind certain loans. If a buyer defaults very quickly—often within the first 90 days—the lender may force the dealership to buy the loan back. That means the dealership may become financially responsible for:
- The unpaid balance
- Repossession costs
- Vehicle depreciation
- Fraud investigation losses
When multiple vehicles are involved, the losses can reach hundreds of thousands or even millions of dollars.
5. These Cases Often Become Federal Criminal Investigations
Credit bust-out schemes frequently involve:
- Bank fraud
- Wire fraud
- False statements on loan applications
- Interstate financial transactions
That makes them attractive targets for federal prosecutors.
6. What Should You Do If You’re Caught in One of These Schemes?
If you purchased vehicles under one of these arrangements, don’t assume you are automatically viewed only as a victim. Investigators may ask:
- Did you knowingly submit false information?
- Did you profit from the arrangement?
- Were you aware multiple vehicles were being financed simultaneously?
These are serious questions with serious consequences. If you are contacted by law enforcement, lenders, or federal agents:
- Do not make statements without counsel
- Preserve all communications and documents
- Gather financing records and contracts
- Contact a criminal defense attorney immediately
The earlier you address the situation, the more options you may have.
Barry Wax gives people in trouble the ability to make the right choices and regain control of their lives. If you have been caught up in a credit bust-out investigation involving vehicle financing, Turo rentals, or alleged financial fraud, Barry can help you understand your exposure and protect your future.
FAQs
What is a credit bust-out scam?
It is a fraud scheme where credit is obtained through false information, often to finance vehicles or purchases that quickly go into default.
Are people who buy the cars always considered victims?
Not necessarily. If investigators believe someone knowingly submitted false information, they may face criminal scrutiny.
Why are Turo-related scams increasing?
Car-sharing platforms create an appearance of legitimacy that scammers use to convince people to finance vehicles.
Can dealerships lose money in these cases?
Yes. Dealers may be financially responsible if financed vehicles default shortly after purchase.
What criminal charges can arise from these schemes?
Possible charges include bank fraud, wire fraud, conspiracy, and making false statements on loan applications.
What should I do if federal agents contact me about one of these cases?
Do not speak with investigators without legal counsel. Preserve records and contact a defense attorney immediately.
Copyright © 2026 Law Offices of Barry M. Wax. All rights reserved.
Digital Marketing By 
*Images are obtained under license from Canva and other third-party stock image providers, with attribution included where required.